


We may not have the course you’re looking for. If you enquire or give us a call on 01344203999 and speak to our training experts, we may still be able to help with your training requirements.
Types of Mortgages Explained: Find the Best Fit for You
ByAkhil KLast updated on: 03 October 2026
Types of mortgages include fixed-rate, variable-rate, tracker, discount, and interest-only options, along with specialist types like offset and buy-to-let mortgages, each differing by interest rate structure and repayment method. Understanding these options helps borrowers choose a mortgage that fits their budget and long-term goals.
In This Blog
1. Common mortgage types differ mainly in how their interest rates are structured and how repayments work.2. Fixed, variable and specialist mortgages each suit different financial circumstances and risk preferences.3. Savings, deposit size and borrowing circumstances can all influence which mortgage type is most suitable.4. Some mortgage features offer stability, others offer flexibility or a lower initial deposit requirement.5. Comparing mortgage products involves weighing several factors together, not just the headline interest rate.
Buying a home is one of those exciting life milestones where you imagine new beginnings, cosy rooms, and future memories. But once the conversation shifts to types of mortgages and you hear terms like fixed, tracker or discount rates, things can quickly feel confusing. If you have ever smiled and pretended to understand while planning to Google it later, you are not the only one!
This blog explains different types of mortgages and how to choose the right one. You'll also get a clearer sense of repayment options and which mortgages tend to be easier to qualify for. Let's make your home-buying journey easier and more confident.
Different Types of Mortgages
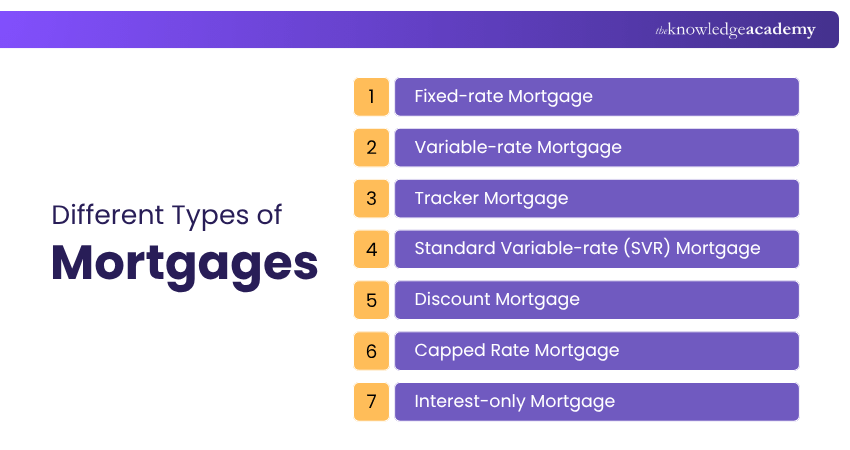
There are seven different types of mortgages: Fixed-rate, variable-rate, tracker, standard, discount, and interest-only. Let's look at those seven types in detail:
1) Fixed-rate Mortgage
Homebuyers prefer a fixed-rate mortgage due to its ability to offer stability in payments. The interest rate is also fixed over a specific period usually two to five years hence repayments made monthly are the same. At the expiry of the fixed deal, borrowers tend to transfer to the standard variable rate of the lender unless they secure a new mortgage agreement which might be higher.
2) Variable-rate Mortgage
A variable-rate mortgage means your interest rate and monthly payments can increase or fall over time. These changes often follow the broader economy and moves in base rates, like decisions from the Bank of England. Variable deals come in different forms, including:
1) Standard Variable Rate (SVR)
2) Tracker mortgages
3) Discount mortgages
4) Capped-rate mortgages
Know the Difference
Variable-rate is a broad category rather than a single mortgage structure. Tracker, SVR, discount and capped-rate mortgages can all involve changing rates, but the way those changes are determined differs between products.
3) Tracker Mortgage
Tracker mortgages follow the Bank of England's base rate in addition to a set percentage. For example, if the base rate is 3.75% and your tracker is "base rate plus 1%," you'd pay 4.75%. Monthly repayments adjust with the base rate. However, some trackers have a "collar," limiting how low the rate can go. After the introductory period (usually two years), you'll switch to the lender's SVR unless you remortgage.
4) Standard Variable-rate (SVR) Mortgage
The default interest rate charged by the lender is the Standard Variable-rate (SVR). This is normally higher than most fixed, tracker, or discount mortgage offers. The SVR is not strictly connected with the base rate of the Bank of England, although lenders have the opportunity to fluctuate it along with the base rate fluctuations. The lender can change its SVR, which can cause borrowers' monthly repayments to increase or decrease.
5) Discount Mortgage
A discount mortgage is a variable-rate loan where your interest rate is the lender’s SVR minus a fixed margin. If the SVR increases, your payments go up. If it decreases, your payments go down. These deals usually have an introductory period of two years. After that, you could be moved to a higher SVR or need to remortgage.
6) Capped Rate Mortgage
A capped-rate mortgage is a variable-rate deal with a maximum rate (the cap), so your interest rate cannot rise above a set level during the deal period. Caps can apply to SVR, tracker, or discount products. Because the lender takes the risk of rates rising above the cap, these deals are now rare, and the cap is often set well above the current rate. Some also include a collar (a minimum rate), so you may not benefit fully if rates fall.
7) Interest-only Mortgage
An interest-only mortgage requires you to pay only the interest each month, without reducing the loan amount. Because the capital remains unpaid, you must have a plan in place to repay the full balance later, such as savings, investments or selling a property. This option is often used for buy-to-let mortgages.
What are the Other Types of Mortgages?
Apart from the standard types of mortgages that we have discussed already, there are a few other types that you should know. These categories are:
1) Offset Mortgages
An offset mortgage is the bridge between your savings and your loan. This reduces the amount of interest you pay. Here are some key points to remember:
1) Your savings are offset against your mortgage balance, which lowers the interest you’re charged.
2) You can access your savings at any time, which offers significant flexibility.
3) The interest on your mortgage is calculated based on the net balance (mortgage amount minus the savings).
4) This is one of the many mortgage types that is ideal for those with substantial savings but who don’t want to tie them up in the mortgage.
5) Compared to standard loans, offset mortgages may come with higher interest rates.
Trainer’s Pro Tip
When comparing an offset mortgage, look beyond the interest saved. Consider the mortgage rate, fees, savings balance and access conditions together to understand whether the arrangement suits your circumstances.
Learn to manage budgets, savings, and investments effectively with our Personal Finance Course – Register today!
2) 95% Mortgages
A 95% mortgage (known as a 95% LTV (Loan-to-Value) mortgage) involves borrowing 95% of the purchase price, which makes the deposit only 5%. Here are some key points to remember:
1) These mortgages are typically aimed at those first-time homebuyers who may not have saved enough for a large deposit.
2) They often have higher interest rates to balance out the lender's increased risk.
3) For example, on a £200,000 home, a 5% deposit would be £10,000, and the mortgage would cover the remaining £190,000.
4) These mortgages can be an option for eligible buyers with smaller deposits who want to enter the property market.
3) Buy-to-let Mortgages
Buy-to-let mortgages are for those individuals who want to purchase property and then rent it out to tenants. Here are the main points to remember:
1) They usually require a larger deposit than residential mortgages.
2) Typically, the interest rates on buy-to-let mortgages are higher than those on standard home loans.
3) Lenders evaluate the expected rental income to decide how much they will be able to lend.
4) Lenders typically assess whether the expected rental income provides sufficient coverage for the mortgage payments, with the required level varying by lender and borrower circumstances.
4) Flexible Mortgages
Flexible mortgages in the UK are home loans that allow borrowers to make adjustments to their repayments, offering greater control and financial freedom. Here are the main points to remember:
1) Flexible mortgages enable you to overpay, underpay or take payment holidays, depending on the lender’s terms.
2) They are ideal for borrowers with variable incomes, such as freelancers or self-employed individuals.
3) Interest is typically calculated daily, so overpayments reduce the balance and total interest paid faster.
4) Many Flexible mortgage types include a “borrow back” feature, letting you access previous overpayments if needed later.
5) Some lenders offer offset accounts, where your savings reduce the interest charged on your mortgage.
5) Joint Mortgages
This kind of mortgage is taken out by two or more individuals, such as couples or family members, to buy a property together. These points will explain the idea behind joint mortgages:
1) This type of mortgage is common among couples, friends, or family members sharing home ownership.
2) Combining financial resources may allow applicants to qualify for a larger mortgage than they could individually.
All borrowers are responsible for meeting the mortgage obligations. Lenders assess the applicants' combined income alongside their expenditure, debts, credit histories and other affordability factors when deciding how much they may borrow.
6) Guarantor Mortgages
A guarantor mortgage allows a family member or close relative to support a borrower who may struggle to qualify for a home loan independently. The guarantor agrees to cover repayments if the borrower is unable to meet them, helping lenders reduce risk.
1) The guarantor agrees to take care of your mortgage payments in case you are unable to, reducing the lender’s risk.
2) Guarantor mortgage types are often utilised by first-time buyers or those with a deficient credit history or a small deposit.
3) This type of mortgage may help some borrowers qualify with a smaller deposit or where they might otherwise struggle to meet a lender's criteria.
4) Some deals allow the guarantor’s responsibility to be removed once you’ve built up enough equity or a solid payment history.
It’s important for both parties to understand the risks involved, especially for the guarantor.
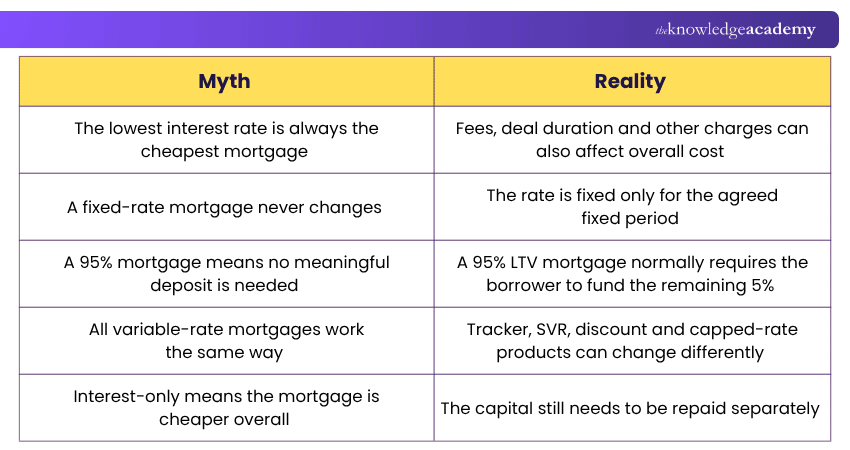
Mortgage types differ in more than their headline interest rates. Repayment structure, fees, flexibility, deposit requirements and how rates can change all matter. Understanding these differences can help you compare available products based on your financial circumstances.
Learn mortgage practices and financial regulations with the CeMAP Course (Level 1,2 And 3) - Join now!

Akhil K is a Copywriter and Video Editor with experience in content creation, visual storytelling, advertising and brand communication. His background in journalism, research and audience-focused communication strengthens his ability to create clear and engaging Business Skills content.
View Detail

 If you wish to make any changes to your course, please


