



We may not have the course you’re looking for. If you enquire or give us a call on 01344203999 and speak to our training experts, we may still be able to help with your training requirements.
What is a Mortgage: Understanding Key Concepts
ByNaveena VenkatesanLast updated on: 30 September 2026
A mortgage is a type of loan used to buy a home or refinance a property, where the borrower repays the amount with interest over an agreed time period. The lender provides the remaining property cost after the deposit is paid up front. Borrowers repay the mortgage in monthly instalments with added interest over time.
Quick Look
1. A mortgage helps buyers purchase property by borrowing money secured against the home.2. Mortgage repayments may include both the borrowed amount and interest, depending on the repayment type.3. Common mortgage options include fixed-rate, tracker, variable-rate, repayment, and interest-only mortgages.4. Deposit size, Loan-to-Value (LTV), interest rates, and fees can affect the overall mortgage cost.5. Mortgage approval usually involves affordability checks, credit assessment, property valuation, and a formal offer.
Dreaming of owning a home but worried about the huge price tag? You’re not alone. For most people, buying a house outright isn’t possible, and that’s where a mortgage steps in. It’s more than just a loan; it’s the bridge between renting and finally having a place you can call your own.
In this blog, we’ll answer what a mortgage is, how it works, its main types and mortgage repayments. By the end, you’ll clearly understand how to choose the right one for your needs. Let's get started!
What is a Mortgage?
A mortgage is a type of loan used to help people buy a property, such as a house or flat. Since buying a home is expensive, borrowers usually pay a deposit up front and borrow the remaining amount from a bank or lender. The loan is secured against the property, which means that the lender can take ownership if the borrower fails to repay the mortgage.
Mortgage repayments are usually made monthly over a long period, such as 20 to 30 years. Different types of mortgage options are available, and the type chosen affects the interest rate, repayment method, and overall borrowing costs.
How Does a Mortgage Work?
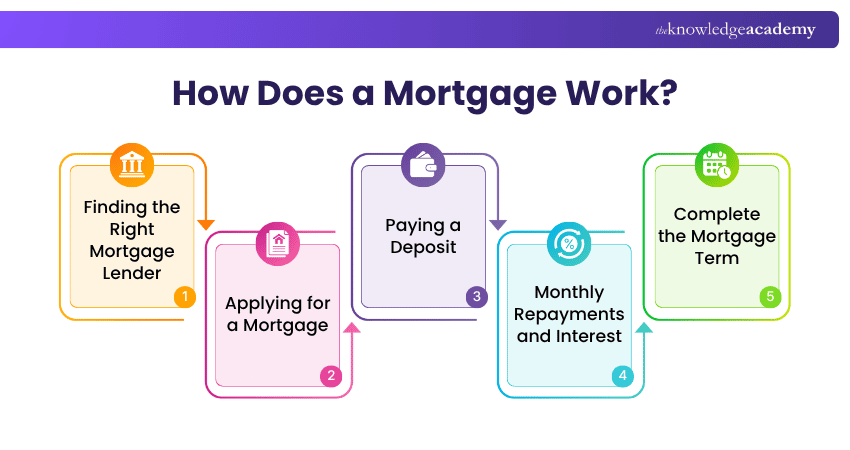
A mortgage is more than just borrowing money to buy a home. It involves a few important steps, from choosing the right lender to paying back the loan over time. Here's a simple breakdown of how the mortgage process works:
1) Finding the Right Mortgage Lender
Before applying for a mortgage, borrowers should compare lenders, interest rates, repayment terms, and loan features to choose a suitable option.
a) Compare mortgage interest rates from different lenders
b) Review repayment terms, loan features, and lender support
c) Choose a lender that offers clear guidance and suitable mortgage options
2) Applying for a Mortgage
After selecting a lender, the borrower submits a mortgage application. The lender reviews details like income, employment status, credit history, and expenses to check loan eligibility.
a) Submit documents such as payslips, bank statements, and identification proof
b) Complete the mortgage application process with the lender
c) Wait for the lender to assess and approve the mortgage loan
3) Paying a Deposit
A deposit is the amount a buyer pays towards the purchase price of a property, with the remaining amount typically covered by a mortgage. A larger deposit means you need to borrow less and usually results in a lower Loan-to-Value (LTV) ratio, which may give you access to a wider range of mortgage products and potentially more competitive rates.
a) Most people pay at least 5% to 20% of the home's price
b) A larger deposit can lower your monthly payments
c) You need to save this money before applying
Trainer’s Tip: Use the Loan-to-Value (LTV) ratio when comparing mortgage options. A larger deposit generally results in a lower LTV, which may give you access to a wider range of mortgage products and potentially more competitive rates.
4) Mortgage Approval Process
The lender assesses the borrower’s financial circumstances and the property before deciding whether to approve the mortgage. If approved, the lender provides the mortgage offer outlining the loan amount, interest rate, repayment terms, and other applicable conditions.
a) The lender checks affordability and repayment ability
b) Property valuation may take place during the approval process
c) Approved borrowers receive a mortgage offer
5) Complete the Property Purchase
After mortgage approval, the lender provides the funds to purchase the property, which then acts as security for the loan.
a) The lender transfers funds for the property purchase
b) Ownership of the property is completed legally
c) The property remains linked to the mortgage until repayment ends
6) Monthly Repayments and Interest
Each month, you pay back part of the loan plus some interest. The interest is the extra money the lender charges for letting you borrow. Your monthly amount depends on how much you borrowed and the interest rate.
a) Payments include the loan amount and interest
b) Interest can be fixed or change over time
c) Always check how much you’ll pay monthly
7) Complete the Mortgage Repayment
Once all mortgage payments are completed, the borrower fully owns the property. The lender’s legal claim over the property is removed, and the mortgage is officially closed.
a) The final payment clears the mortgage loan
b) The borrower gains full ownership of the property
c) The lender no longer holds security over the property
Become familiar with data collection, analysis techniques, and recapitulation. Join our Real Estate Risk Management Training today.
Types of Mortgages
There are different types of mortgages available to suit different financial situations and preferences. Here are some common types:
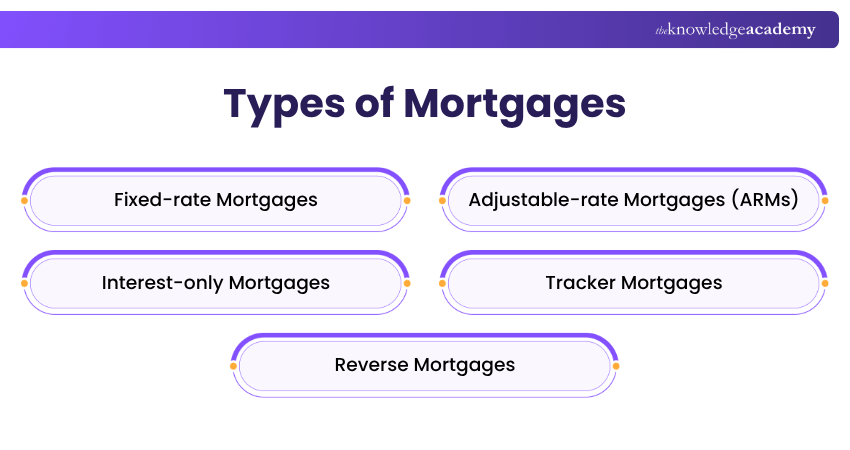
1) Fixed-rate Mortgages
A fixed-rate mortgage keeps the interest rate the same for an agreed period, such as two or five years. This can make monthly payments more predictable during the fixed-rate period. Once the period ends, the borrower may need to switch to a new deal or move to the lender's applicable reversion rate.
Example:
a) You pay £600 every month for 25 years
b) Best for people who like steady payments
c) Best for people who like steady payments
2) Adjustable-rate Mortgages (ARMs)
With an adjustable-rate mortgage, the interest rate can go up or down over time. It often starts with a low rate, then changes based on the market. This type might save money at first but can become more expensive later.
Example:
a) 2.5% rate for the first 2 years, then it may rise
b) Good if you plan to move in a few years
c) Risky if interest rates go high
3) Interest-only Mortgages
An interest-only mortgage requires the borrower to pay the interest each month while the capital remains outstanding. The borrower must have a suitable plan to repay the capital at the end of the mortgage term.
Example:
a) Pay only interest for 5 years, then full payments
b) Useful if your income will grow later
c) Not ideal for long-term home ownership
4) Tracker Mortgages
A tracker mortgage has an interest rate that follows a reference rate, typically with a set percentage added to it. When the reference rate changes, the mortgage rate and monthly repayments may also change. Unlike a fixed-rate mortgage, the interest rate is not fixed for the agreed period.
Example:
a) Your rate is 1% above the base rate
b) Good if base rates stay low
c) Payments can rise suddenly if the base rate increases
5) Reverse Mortgages
A reverse mortgage allows eligible homeowners to borrow against the value of their property while continuing to live in it. Depending on the product, the funds may be received as a lump sum or in regular payments, with repayment typically becoming due when the homeowner sells the property, moves out, or dies.
Example:
a) Borrow £40,000 while still living in your home
b) No monthly repayments needed during your lifetime
c) Usually for people aged 55 or older who own their home
Master income capitalisation, site analysis, and comparative sales techniques. Join our Real Estate Valuation and Appraisal Training today.
What is a Repayment Mortgage?
A repayment mortgage, also known as a capital and interest mortgage, requires the borrower to repay both the amount borrowed and the interest charged by the lender through regular monthly payments. At the beginning of the mortgage term, a larger portion of each payment may go towards interest, while more of the payment goes towards reducing the outstanding balance as the mortgage progresses.
If the borrower maintains the agreed payments throughout the mortgage term, the mortgage balance should be fully repaid by the end of the term, provided the mortgage is not changed or extended. This means the borrower will have repaid both the original amount borrowed and the interest due under the mortgage.
How Many People Can Be on a Mortgage?
The number of people who can be named on a mortgage depends on the lender and the mortgage product. Some lenders allow multiple applicants to apply for a joint mortgage, which can be used by couples, family members, or other people buying a property together.
Having multiple borrowers may increase the amount they can borrow because lenders may consider the applicants’ combined income and financial circumstances. However, everyone named on the mortgage is responsible for meeting the agreed repayments and other obligations under the mortgage.
Gain expertise in assessing mortgage products and market trends. Join our CeMAP Course (Level 1,2 And 3) today.

Naveena Venkatesan is a Content Editor with 2+ years of experience in content writing, editing and linguistic quality assurance. Her research, fact-checking and editorial experience enable her to develop accurate, accessible resources across Business Skills, Human Resources, and Accounting and Finance.
View Detail

 If you wish to make any changes to your course, please


