


We may not have the course you’re looking for. If you enquire or give us a call on 01344203999 and speak to our training experts, we may still be able to help with your training requirements.
Mortgage Life Cycle: Explained in Detail
ByNaveena VenkatesanLast updated on: 03 October 2026
Explore the concept of mortgage life cycle in detail and fulfil your homeownership dreams. This cycle starts when an individual decides to purchase a house and approaches a financial institution for a loan. This blog delves into every stage of this cycle, from pre-application and approval to closure and repayment.
Before We Dive In
1. The mortgage life cycle covers every stage from initial planning to ongoing repayment.2. UK buyers usually begin by reviewing affordability, deposit requirements, and a Mortgage in Principle.3. The lender then assesses the application, supporting documents, credit history, and property valuation.4. Once approved, a formal Mortgage Offer is issued before exchange and completion.5. After completion, the borrower enters the repayment stage based on the agreed Mortgage terms.
Home ownership - It's the ultimate dream. The key to your home is more than just a piece of metal; it's the gateway to personal stability that unlocks a haven for your safety, protection, and lifelong memories. Embarking on the journey of home ownership is a thrilling adventure whose many twists and turns along the way are guided by the mortgage life cycle. From securing a loan to making that final payment, this cycle is a roadmap to achieving your dream home.
Interestingly, for more than a decade, the Mortgage rates in the UK were on a downward trend that improved the affordability of housing loans. This blog delves into what the mortgage life cycle entails, encompassing everything from the pre-application stage to the repayment stage and will help you understand the homeownership process better.
Pre-application Stage
The pre-application stage marks the beginning of the mortgage life cycle and is a crucial phase for prospective borrowers. During this stage, individuals or couples assess their financial situation, research lenders, and evaluate Mortgage options, all with the eventual goal of executing a Mortgage Deed. It involves understanding personal finances, budgeting, and determining creditworthiness. Here are some key steps involved with this stage:
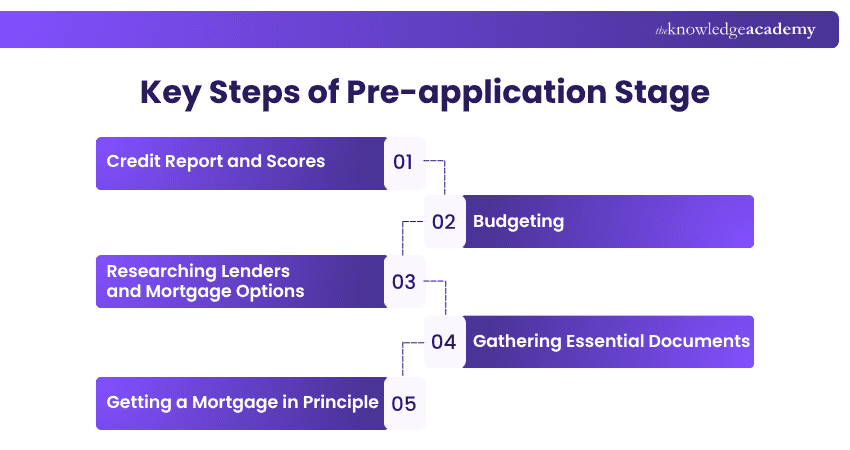
a) Credit Report and Scores: One of the first steps in the pre-application stage is obtaining a credit report and reviewing credit scores. This allows potential borrowers to assess their creditworthiness and identify any areas that need improvement. Addressing any issues, such as paying off outstanding debts or correcting errors on the credit report, can help improve the chances of obtaining a favourable Mortgage offer.
b) Budgeting: Budgeting is another important aspect of the mortgage life cycle’s pre-application stage. Prospective borrowers should carefully evaluate their income, expenses, and savings to determine how much they can comfortably afford to borrow. This involves considering not only the monthly Mortgage payment but also other homeownership costs, such as Council Tax, buildings insurance, maintenance, and service charges where applicable.
c) Researching Lenders and Mortgage Options: Researching lenders and Mortgage options is a critical part of the pre-application stage. Different lenders offer varying Mortgage products with different interest rates, loan terms, and eligibility requirements. By comparing options and obtaining quotes from multiple lenders, borrowers can find the best Mortgage deal that suits their needs and financial situations.
d) Gathering Essential Documents: Additionally, gathering essential documents is crucial during this stage. Lenders typically require documents such as payslips, bank statements, proof of identity, proof of deposit, and other financial information to assess the applicant’s income, expenditure, and ability to repay the Mortgage. Collecting these documents in advance can expedite the application process.
e) Getting a Mortgage in Principle: A Mortgage in Principle, also called an Agreement in Principle or Decision in Principle, gives an estimate of how much a lender may be willing to lend based on initial financial information. It is not a formal Mortgage offer, but it can help prospective buyers understand their budget before making a full application.
Before You Apply
Check:1. Deposit amount2. Income and expenditure3. Credit history4. Mortgage in Principle5. Additional buying costs
Application and Approval Stage
Once the pre-application stage is complete, the next crucial phase of the mortgage life cycle is the application and approval stage. During this stage, prospective borrowers formalise their Mortgage application and go through the evaluation process by the lender. Here are the major steps associated with this stage:
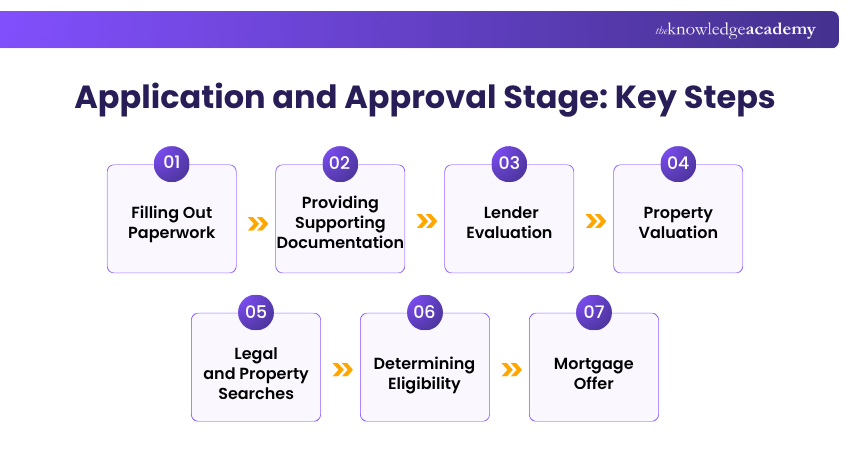
a) Filling Out Paperwork: The borrower initiates the application by completing the necessary paperwork the lender provides. This includes financial details, personal information, employment history, and other relevant data. You must be meticulous and precise to avoid any delays or complications.
b) Providing Supporting Documentation: In this step, applicants typically provide recent payslips, bank statements, proof of identity, proof of deposit, and other supporting financial documents. Self-employed applicants may also need to provide business accounts and tax documents such as SA302 forms. These documents verify your income, assets, and liabilities, helping the lender assess your financial stability and repayment ability.
c) Lender Evaluation: After submission, the lender reviews the applicant’s credit history, income, expenditure, employment status, existing financial commitments, and other relevant factors to assess affordability and eligibility. They may contact employers, credit agencies, and financial institutions to verify the provided information.
d) Property Valuation: The lender arranges a property valuation to confirm that the property is worth enough to support the Mortgage. This helps the lender assess the property’s suitability as security for the loan. Buyers may also choose to arrange a separate home survey for a more detailed assessment of the property’s condition.
e) Legal and Property Searches: The buyer’s solicitor or conveyancer checks the property’s title and carries out relevant searches, such as local authority, drainage and water, and environmental searches. These checks help identify ownership details, restrictions, legal issues, and other factors that could affect the purchase or the lender’s security.
f) Determining Eligibility: Based on its assessment, the lender decides whether the applicant meets its lending criteria and determines the Mortgage terms, including the loan amount, repayment period, interest rate, and Mortgage type, such as fixed-rate or variable-rate.
g) Mortgage Offer: The final step of this stage involves the lender issuing a formal Mortgage Offer once the application, affordability checks, and property valuation have been completed. This document outlines the loan's terms and conditions, including the loan amount, interest rate, monthly payment, and other relevant details. Review the offer carefully and seek clarification if needed.
Mortgage Process Check
Applicant provides documents → Lender assesses affordability → Property is valued → Mortgage Offer is issued
Closing Stage
The closing stage, commonly referred to as completion in the UK, is when the property purchase is finalised and ownership transfers to the buyer. Before completion, the buyer’s solicitor or conveyancer checks that the Mortgage offer, searches, contracts, and required funds are in place. This stage is detailed below:
|
Steps of the Closing Stage
|
Timeframe
|
|
Reviewing the contract and final documents
|
Before exchange of contracts
|
|
Exchanging contracts
|
Once legal checks and mortgage arrangements are complete
|
|
Agreeing the completion date
|
Usually at exchange of contracts
|
|
Transferring the remaining funds
|
On the completion date
|
|
Completing the transfer of ownership
|
On the completion date
|
a) Exchange of Contracts: The buyer and seller sign and exchange contracts, making the transaction legally binding.
b) Completion Date: A completion date is agreed between the buyer and seller.
c) Transfer of Funds: On completion day, the buyer’s solicitor or conveyancer receives the Mortgage funds from the lender and transfers the purchase money to the seller’s solicitor.
d) Transfer of Ownership: Once the funds are received, the property transfer is completed and the buyer becomes the legal owner.
e) Receiving the Keys: The estate agent or seller releases the keys after completion is confirmed.
f) Post-completion Formalities: The solicitor or conveyancer handles matters such as Stamp Duty Land Tax where applicable and registers the change of ownership with HM Land Registry.
Repayment Stage
After the closing stage, borrowers enter the repayment stage of the mortgage life cycle. This stage spans the entire duration of the Mortgage loan and involves making regular monthly payments to the lender. For a repayment Mortgage, each monthly payment includes both capital and interest, gradually reducing the amount owed over the Mortgage term.
With an interest-only Mortgage, monthly payments generally cover only the interest, while the capital is repaid separately at the end of the term. The interest is the cost of borrowing the money and is calculated based on the outstanding principal balance and the interest rate. These are the points to remember about this stage:
a) Timely Payments: The repayment stage of the mortgage life cycle requires borrowers to make timely payments to the lender. It’s essential to establish a system to ensure payments are made on time, such as setting up automatic payments or creating reminders. Late or missed Mortgage payments can lead to additional charges and may negatively affect the borrower’s credit record.
b) Repayment Schedule: For a repayment Mortgage, the balance between capital and interest changes over time. In the early years, a larger share of each payment typically goes towards interest, while later payments contribute more towards reducing the capital balance.
c) Options for Borrowers: During the repayment stage, borrowers should be aware of their options. Some borrowers choose to make additional principal payments to pay off the Mortgage early and save on interest costs. This can be done by making extra payments or increasing the monthly payment amount.
d) Remortgaging Considerations: Another option is remortgaging, which involves switching the existing Mortgage to a new deal, either with the current lender or a different lender. This may help borrowers obtain a different interest rate, repayment structure, or Mortgage term. However, fees, Early Repayment Charges, and eligibility requirements should be considered before switching.
e) Monitoring Mortgage Account: Throughout the repayment stage, borrowers should stay informed about their Mortgage account. This includes regularly reviewing statements, verifying the accuracy of payments applied, and contacting the lender if any discrepancies or concerns arise.
f) Financial Management: Additionally, borrowers should be proactive in managing their finances to ensure the ability to make Mortgage payments.
Repayment Reality
A repayment Mortgage gradually reduces both capital and interest, while an interest-only Mortgage generally leaves the capital to be repaid separately at the end of the term.
Develop the knowledge needed to understand mortgage products, processes, and professional advice with our CeMAP Course (Level 1, 2 and 3) - Join now!

Naveena Venkatesan is a Content Editor with 2+ years of experience in content writing, editing and linguistic quality assurance. Her research, fact-checking and editorial experience enable her to develop accurate, accessible resources across Business Skills, Human Resources, and Accounting and Finance.
View Detail

 If you wish to make any changes to your course, please


