


We may not have the course you’re looking for. If you enquire or give us a call on 01344203999 and speak to our training experts, we may still be able to help with your training requirements.
Mortgage vs Loan: A Comprehensive Comparison for Borrowers
ByNaveena VenkatesanLast updated on: 03 October 2026
A mortgage is a secured loan used mainly to purchase property, while other loans may be secured or unsecured and used for a wider range of purposes. Mortgages generally involve larger amounts and longer repayment terms, while personal loans usually involve smaller sums and shorter repayment periods.
Dreaming of your own home or planning to borrow money for big goals? You’ve probably come across the terms mortgage and loan. These terms are often used interchangeably, but they’re not quite the same. Understanding the difference between mortgage vs loan can save you confusion, time, and potentially thousands of pounds.
This blog dives deep into the key distinctions between mortgage vs loan. In this comprehensive comparison, we’ll break down their key features, uses, benefits, interest rates, repayment terms, and more to help you make smarter borrowing decisions. So read on and learn how to choose the option that fits your needs best!
What is a Mortgage?
A mortgage is a type of secured loan used to buy or refinance property, with the property itself acting as security for the borrowing. The lender places a legal charge over the property, meaning it may ultimately seek possession if repayments are not maintained and other solutions cannot be agreed.
When assessing a mortgage application, UK lenders typically consider income, regular expenditure, existing debts, credit history, deposit, and overall affordability. They will also usually arrange or require a property valuation before confirming how much they are prepared to lend.
What is a Loan?
A loan is an agreement in which a lender provides money to a borrower who agrees to repay it, usually with interest, over an agreed period. Loans can be secured against an asset or unsecured, depending on the product and lender.
Personal loans are commonly unsecured and are normally repaid through fixed monthly payments over a set term. Secured loans use an asset, such as a home, as security and may allow larger amounts or longer repayment periods.
Differences Between Mortgage and Loan
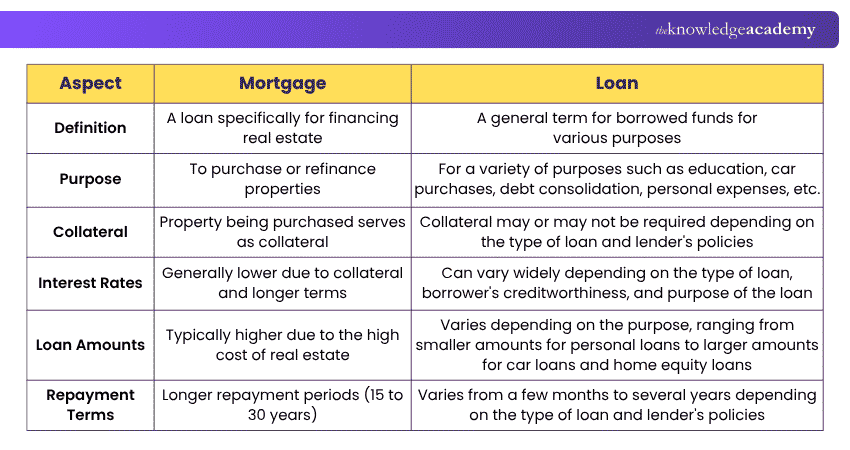
The table showing the aspects of mortgage and loan will help you understand the distinctions between them:
Which option is being described?
1.Property used as security → Mortgage2.Unsecured lump-sum borrowing → Personal Loan3.Asset pledged as security → Secured Loan4. No asset pledged → Unsecured Loan
Mortgage vs Loan: Eligibility Requirements
Mortgage and loan eligibility varies by lender, product, and individual circumstances. Common factors include income, expenditure, existing debts, credit history, employment status, and the amount being borrowed.
For mortgages, lenders carry out a detailed affordability assessment and consider household income, regular spending, existing credit commitments, deposit, and the property being purchased. There is no universal UK minimum credit score required for a mortgage.
For personal loans, lenders typically assess affordability, income, existing borrowing, and credit history before deciding whether to lend and what rate to offer.
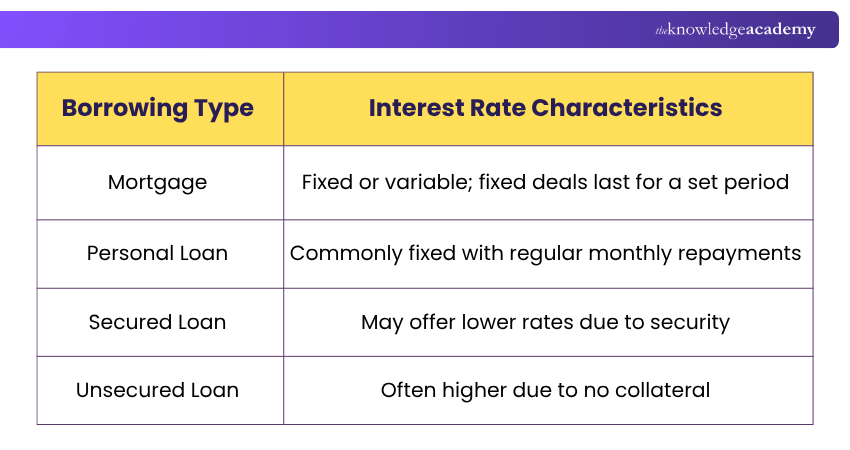
Mortgage vs Loan: Interest Rates
The following differential feature between mortgages and loans focuses on interest rates. Here are the key points to remember:
1) Mortgage rates may be fixed or variable, depending on the product.
2) Fixed-rate mortgages keep the same interest rate for an agreed deal period, commonly between two and ten years.
3) After a fixed deal ends, borrowers may move onto the lender’s Standard Variable Rate unless they arrange another deal.
4) Tracker and other variable-rate mortgages can rise or fall as interest rates change.
5) Personal loans commonly use fixed monthly repayments, although some products may have variable rates.
6) Secured borrowing often offers lower rates than comparable unsecured borrowing because the lender has an asset as security.
7) Borrowers should compare the interest rate, APR or APRC, fees, repayment term, and total borrowing cost rather than the headline rate alone.
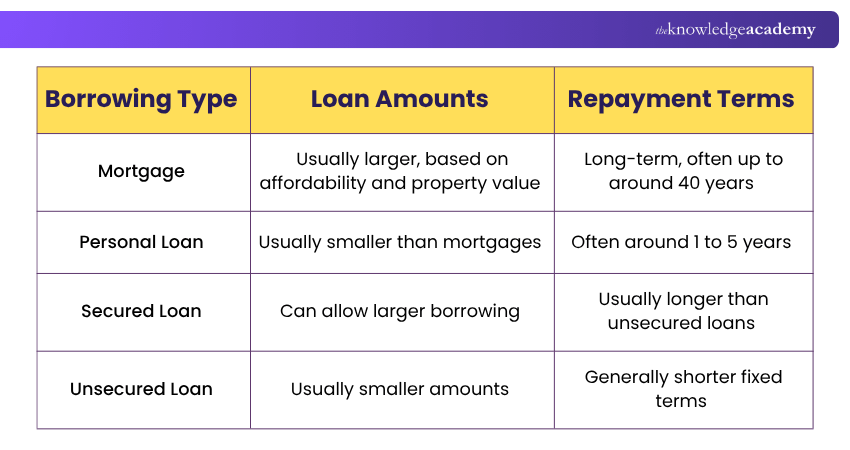
Mortgage vs Loan: Loan Amounts and Repayment Terms
Here are the key points to remember pertaining to Loan amounts and repayment terms related to mortgage and loan:
1) Mortgages generally involve larger borrowing amounts because they are used to finance property purchases.
2) The amount available depends on factors such as income, affordability, deposit, property value, and lender criteria.
3) UK mortgage terms vary and can range from a few years to around 40 years, depending on the lender and borrower.
4) A longer mortgage term can reduce monthly repayments but usually increases the total interest paid.
5) Personal loans usually involve smaller sums and shorter terms than mortgages.
6) Many personal loans are repaid over around one to five years, although terms vary between lenders and products.
7) Borrowers should compare total repayment cost as well as the monthly payment.
What are the Types of Mortgages?
There are various kinds of Mortgages through which the Loan amount varies depending on the rate of interest, the size of the term, and much more. Let us look at a few of them to gain clarity:
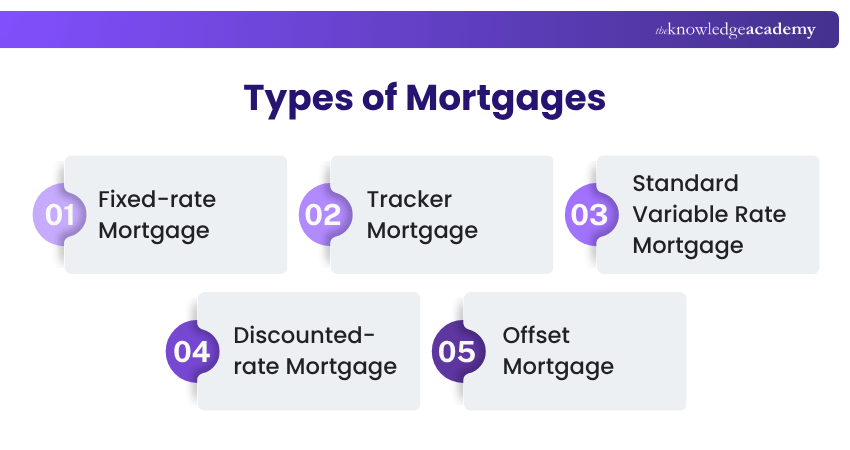
1) Fixed-rate Mortgage: The interest rate remains unchanged for a set deal period, commonly two, five, or sometimes ten years, giving borrowers predictable monthly repayments during that period.
2) Tracker Mortgage: The interest rate follows another rate, usually the Bank of England base rate, plus a set margin. Payments can therefore rise or fall.
3) Standard Variable Rate Mortgage: The lender sets this variable rate and can change it. Borrowers often move onto the SVR after an introductory mortgage deal ends.
4) Discounted-rate Mortgage: The borrower receives a discount from the lender’s SVR for a specified period, so repayments can still change if the SVR moves.
5) Offset Mortgage: Savings held in a linked account are offset against the mortgage balance when calculating interest, potentially reducing the interest charged.
Build smarter borrowing and debt management skills with our Personal Finance Course – Join now!
What are the Types of Loans?
Let us look at a few types of Loans to gain clarity on which are suitable for your needs:
Revolving Credit vs Fixed-term Loans
Revolving credit allows borrowers to access funds repeatedly up to an agreed credit limit, repay what they have used, and borrow again while the account remains open and within its terms. Credit cards and overdrafts are common examples of revolving credit.
Fixed-term loans provide a set amount that is repaid over an agreed period through scheduled repayments. Unlike revolving credit, amounts repaid are not normally available to borrow again unless the product specifically allows further borrowing. For example, repaying part of a standard mortgage balance does not usually make that amount automatically available to borrow again.
Secured vs Unsecured
Loans can broadly be classified as secured or unsecured. A secured Loan needs collateral like a house or car, while an unsecured Loan does not. With unsecured Loans, lenders face more risk since there’s no asset to claim if the borrower cannot repay. Because of this, unsecured Loans typically have increased interest rates, smaller amounts, and depend heavily on the borrower’s income, credit report, and rating. Examples include personal Loans, overdrafts, and credit cards.
Secured Loans (collateral Loans) are backed by an asset offered as security. Mortgages and auto Loans are common examples. Since lenders face less risk, they are more willing to provide larger amounts at lower interest rates. However, if the borrower defaults, the lender has the right to claim or sell the asset used as collateral under the Loan agreement.
Gain expertise in assessing Mortgage products and market trends. Join our CeMAP Course (Level 1,2 and 3) Training now!
Keep This in Mind
1. A mortgage is a type of secured loan.2. Personal loans are usually unsecured and shorter-term.3. Compare APRC for mortgages and APR for loans.4. Check fees, repayment terms, and total borrowing costs.5. Secured borrowing puts the underlying asset at risk.6. Mortgage eligibility depends heavily on affordability and lender criteria.

Naveena Venkatesan is a Content Editor with 2+ years of experience in content writing, editing and linguistic quality assurance. Her research, fact-checking and editorial experience enable her to develop accurate, accessible resources across Business Skills, Human Resources, and Accounting and Finance.
View Detail

 If you wish to make any changes to your course, please


