


We may not have the course you’re looking for. If you enquire or give us a call on 01344203999 and speak to our training experts, we may still be able to help with your training requirements.
What is a Mortgage Deed: An Ultimate Guide
ByNaveena VenkatesanLast updated on: 30 September 2026
A mortgage deed is a legal document securing a loan against a property, giving the lender rights until the borrower fully repays the mortgage. It outlines repayment terms and responsibilities for both parties clearly and transparently. It also allows the lender to take legal action if the borrower does not repay.
Overview
1. A mortgage deed creates a legal connection between the mortgage and the property used as security.2. It establishes important rights and obligations relating to the borrower and lender.3. The deed must be properly executed for it to operate as intended.4. Registration records the lender’s legal charge against the registered property.5. Borrowers should review the deed carefully and clarify anything they do not understand before signing.
Buying a home is a thrilling experience, but the paperwork go with it? Not so much. This is where the mortgage deed comes into play, becoming the backbone of your home loan agreement. This powerful legal document ties your property to your lender, setting out rights, responsibilities, and protections for both sides.
Understanding what is a mortgage deed can save you from hidden pitfalls and future disputes. In this blog, you will learn about the mortgage deed, its components, importance, and more. Keep reading ahead to learn more!
What is a Mortgage Deed?
A mortgage deed is a legally binding document that secures a loan by using a borrower’s property as collateral. It confirms that the borrower agrees to pledge their property to the lender in return for the loan. The document outlines the loan terms, repayment plan, and the rights of both the borrower and the lender. It also gives the lender a legal interest in the property, allowing them to take action, such as foreclosure, if the borrower fails to repay the loan.
Legal Framework: Why a Mortgage Deed is Required in UK Property Law?
A mortgage deed plays an integral role in safeguarding the rights of both the borrower and the lender under UK property law. It is governed by two important legal acts:
1) Law of Property Act 1925: Defines how property ownership and mortgage rights are developed and transferred.
2) Land Registration Act 2002: It makes sure mortgage deeds are recorded with HM Land Registry to make them legally enforceable.
For a mortgage to be verifiable in the UK, the deed must be signed by the borrower, witnessed, and registered. Without proper legal registration, the lender might struggle to enforce rights. This is why borrowers must look for guidance from a solicitor to ensure the process is completed correctly and is legally secure.
How Does a Mortgage Deed Work?
A simplified journey looks like this:
Mortgage is approved↓Mortgage deed is prepared↓Borrower reviews the deed↓Deed is signed and witnessed↓Lender’s charge is registered↓Property secures the mortgage↓Mortgage is repaid↓Registered charge is discharged
Components of a Mortgage Deed
The mortgage deed has several vital features that define the agreement made between the lender and the borrower. This document is essential in various mortgage arrangements, including a reverse mortgage, where homeowners can convert home equity into cash. Let's explore each component in detail:
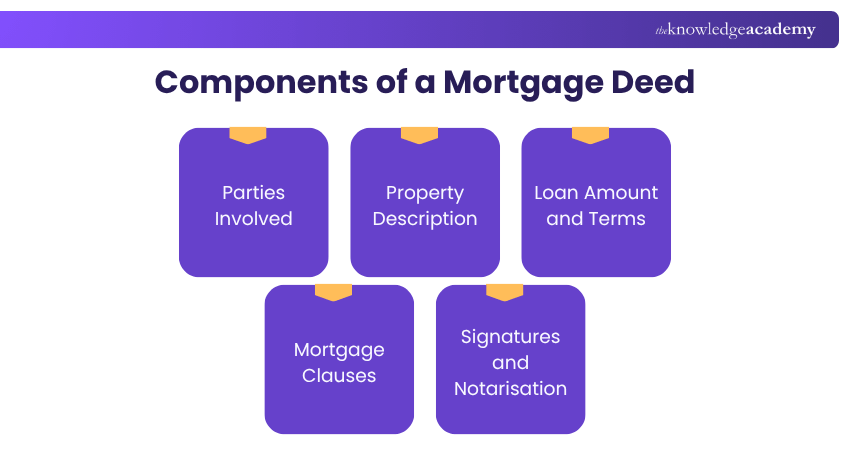
1) Parties Involved
The mortgage deed also seeks to establish the parties to the contract: the giver of the mortgage (the mortgagor) and the recipient of the mortgage (the mortgagee). It gives their names, physical addresses, and more information, including their legal status/ entity type.
2) Property Description
This document usually accompanies the description of the property that the borrower is offering as security for his or her loan. This usually contains the physical location of the property, the coordinates, and the legal description of the property.
3) Loan Amount and Terms
The mortgage deed also notes the specific sum of money that the borrower is to pay the lender as a loan. It also gives details on how repayment is to be made, the rate of interest, and the terms of payment, whether daily, weekly, monthly, or quarterly, among others. Some of the terms and conditions may consist of fines for late payments, extra payments before the due date, or variable percentage interest rates based on the agreement.
4) Mortgage Clauses
Other Mortgage clauses which may be incorporated in the deed to clarify the relations and responsibilities of the parties are- For example:
a) Acceleration Clause: With this provision, the lender could demand the repayment of the entire outstanding loan if the borrower is noncompliant with the terms or has breached the agreement in some manner.
b) Due-on-sale Clause: This one specifically focuses on redeeming the loan in the event of the sale or transfer of the property. It safeguards the interests of the lender and guarantees that the borrower does not take control over subsequent reimbursement.
c) Insurance and Taxes Clause: Through the mortgage deed the borrower may be required to keep the property insured and incur the cost of property taxes for the protection of the Mortgage lender’s security.
5) Signatures and Notarisation
A property’s legal transfer is valid only when the mortgage deed is signed by both parties, that is, the borrower and the lender. The signature verifies that both parties have consented to the provisions. In some jurisdictions, a witness or notary seal is required to make the deed legally enforceable.
Expert Insight
Refinancing, changing lenders or repaying a mortgage can affect the security registered against the property. Check that the relevant records are updated correctly when significant changes occur.
Recording and Registration of a Mortgage Deed
Recording and registration of a mortgage deed is a crucial process that legally documents the Mortgage agreement with the appropriate government office. Here are the steps for recording and registration:
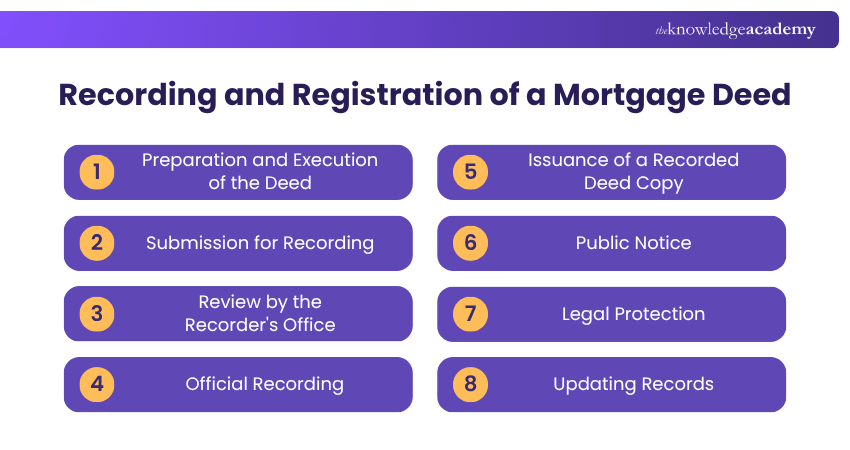
1) Preparation and Execution of the Deed: Draft the mortgage deed with all necessary details, including the parties involved, property description, loan amount, terms, and Mortgage clauses. Both the borrower (mortgagor) and lender (mortgagee) must sign the mortgage deed.
2) Submission for Recording: Submit the executed deed to the local government office responsible for property records, typically the county recorder or land registry office. Pay any required recording fees.
3) Review by the Recorder's Office: The recorder's office reviews the submitted Deed for completeness and accuracy. Any discrepancies or missing information must be corrected before the deed can be recorded.
4) Official Recording: Once approved, the recorder's office officially records the mortgage deed in the public records. The document is assigned a unique recording number and date.
5) Issuance of a Recorded Deed Copy: A copy of the recorded mortgage deed, stamped with the recording details, is issued to both the borrower and lender.
6) Public Notice: Recording the deed publicly announces the lender's interest in the property. It helps protect the lender's rights and ensures transparency in property ownership.
7) Legal Protection: The recorded deed is now a part of the official public record, offering legal protection against fraudulent claims and ensuring the lender's priority in the event of foreclosure.
8) Updating Records: Any subsequent changes to the mortgage, such as refinancing or loan payoff, should also be recorded to keep the public records current and accurate.
Gain in-depth knowledge about the key components of financial systems with our Diploma for Financial Advisers DipFA – join today!
Importance of Mortgage Deed
A mortgage deed is an important piece of legal document. Here is a list of reasons that show the importance of the deed:
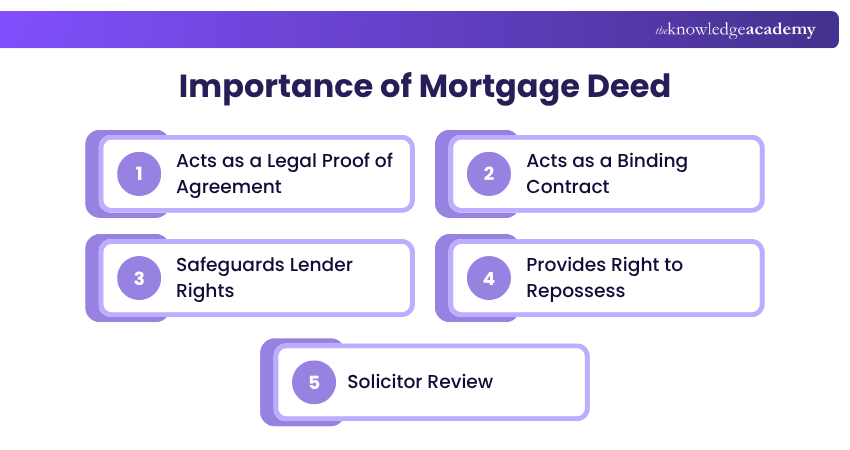
1) Legal Proof of Agreement: Serves as legal proof that you have agreed to the mortgage terms and used your property as security for the loan.
2) Binding Contract: After signing the deed, the terms cannot be changed unless you sign a new deed.
3) Lender Rights: The deed is used by the lender to protect themselves from legal non-compliance issues and protection against non-payment.
4) Right to Repossess: Acts as a lien on the property. It gives the lender legal rights to repossess and sell the home if the borrower defaults or is in arrears.
5) Solicitor Review: A solicitor reviews the mortgage offer and explains the important details before the borrower signs the deed, ensuring transparency and compliance.
What to Consider Before Signing Your Mortgage Deed?
A mortgage deed is a standard part of the mortgage process. However, since it commits you to a long-term financial agreement, it’s essential to review it carefully before signing. If any terms or conditions are unclear, they may cause problems later.
Before signing, make sure to:
1) Double-check all details, including property price, valuation, and your name.
2) Arrange an appropriate witness. This must be an independent person, not a family member.
3) Go through each term and confirm they match your mortgage offer.
Lenders and conveyancers are there to answer questions. So, it’s always better to seek clarification now rather than agree to terms you don’t fully understand.
Trainer’s Insight
Do not treat the mortgage deed as routine paperwork. If names, property information or other relevant details appear incorrect or something is unclear, raise the issue with your conveyancer or solicitor before signing.
How to Choose a Mortgage Deed Witness?
Choosing the right witness for a mortgage deed involves:
1) Legal Eligibility: Ensure the witness is legally eligible, typically over 18 and not a party to the mortgage. They should not have any personal interest in the transaction to avoid any conflict of interest.
2) Credibility: Select a credible and trustworthy individual, preferably someone with a professional background, such as a lawyer, accountant, or a long-time community member. Their credibility can be important if any legal questions arise regarding the signing.
3) Availability: Ensure the witness is available at the time and place of signing to avoid any delays. Coordinate schedules in advance to ensure all parties are present at the same time.
4) Jurisdiction Requirements: Check if there are specific requirements in the jurisdiction regarding who can act as a witness. Some areas may have stringent rules about who qualifies as a witness, such as disallowing family members or those with a financial interest in the transaction.
Who Can Be a Witness for a Mortgage Deed?
A mortgage deed witness must be an independent adult aged 18 or older. They should not be involved in the mortgage and must not be a family member or relative. This ensures the signing is done fairly and without any influence.
Suitable witnesses include a neighbour, colleague, or friend who is not connected to the transaction. They should not live in the property or benefit from the mortgage. Their role is to watch the signing and provide impartial confirmation, helping make the deed legally valid.
Learn how to analyse financial statements with our Financial Management Course – Join today!
Common Legal Issues with Mortgage Deeds (and How to Resolve Them)
Mortgage deeds can sometimes present legal challenges. These can lead to disputes, delays, or even financial loss. Being aware of these risks and knowing how to resolve them can help homeowners steer clear of costly problems. Let's explore them:
1) Unfair Terms in Mortgage Deeds
a) Hidden Fees: Unexpected costs that raise the overall borrowing amount.
b) Early Repayment Penalties: Charges applied for paying off the mortgage ahead of schedule.
c) Unclear Interest Rate Changes: This involves lenders adjusting rates without transparency.
The best way to resolve this is to have a solicitor review the deed before signing. It can highlight and negotiate unfair terms.
2) Disputes Over Ownership or Signatures
a) Missing Signatures: If a co-owner or spouse has not signed, the deed might be invalid.
b) Responsibility Disagreements: This involves disputes over who is legally bound by the mortgage.
The best solution is to have a conveyancing solicitor to ensure all the necessary parties sign correctly. This will help avoid future legal complications.
3) Errors in Registration
a) Incorrect Information: This includes Errors in names, loan amounts or property details.
b) Failure to Register with HM Land Registry: Without this, the lender’s charge may not be enforceable.
The ideal solution is to have a solicitor confirm the accurate registration, thus ensuring the mortgage is legally valid and binding.
Can a Mortgage Lender Refuse to Release the Mortgage Deed?
Yes, a lender can refuse to release mortgage deeds if the loan is not fully repaid, or if legal restrictions apply to the property. Unpaid fees, outstanding debts, or disputes over ownership may also result in delays. In such cases, a solicitor can step in to resolve matters. It's also wise to maintain clear records of payments, as this speeds up the process and reduces complications.
Learn how to analyse financial statements with our Financial Management Course – join today!
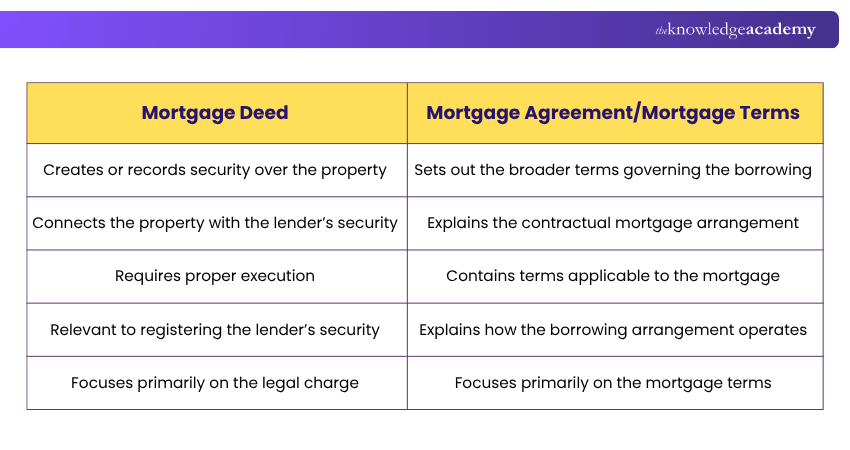
Although closely connected, a mortgage deed and the wider mortgage agreement or mortgage terms should not automatically be treated as the same document. Here are the key distinctions:

Naveena Venkatesan is a Content Editor with 2+ years of experience in content writing, editing and linguistic quality assurance. Her research, fact-checking and editorial experience enable her to develop accurate, accessible resources across Business Skills, Human Resources, and Accounting and Finance.
View Detail

 If you wish to make any changes to your course, please


